GSTR-1 Due Date Alert: Filing Guide, Benefits & Penalties | MLG Associates

All posts by Deepak Singh

GSTR-1 Due Date Alert: Filing Guide, Benefits & Penalties | MLG Associates

GSTR-1 Due Date Alert: Complete Filing Guide, Benefits, and Late Penalties

Tomorrow is the 11th of the month, the statutory deadline for regular taxpayers to file their monthly GSTR-1.

Delaying your GSTR-1 doesn’t just attract late fees—it directly damages your business relationships by freezing your buyers’ input tax credit (ITC). Here is an urgent overview of what GSTR-1 entails, why timely filing matters, and the penalties for non-compliance.
1. What is GSTR-1?

GSTR-1 is a monthly or quarterly return that records all outward supplies (sales) made by a registered taxpayer under GST.

It does not require tax payment directly; instead, it serves as the official declaration of:

  • B2B Invoices: Sales made to other GST-registered entities.

  • B2C Supplies: Large and small sales to unregistered individuals or end consumers.

  • Credit & Debit Notes: Any amendments or rate adjustments made to past sales invoices.

  • Exports & Nil-Rated Supplies: Zero-rated, exempt, and non-GST sales.

Once filed, the data flows automatically into your buyers’ GSTR-2B, enabling them to claim their rightful tax credit.

2. Who Must File by Tomorrow?

  • Monthly Filers: Every registered regular taxpayer with an aggregate turnover exceeding ₹5 Crore (or those who opted for monthly filing under the QRMP scheme) must file on or before the 11th of every month.

  • (Note: Taxpayers enrolled in the quarterly QRMP scheme file quarterly by the 13th of the month following the quarter, but can upload B2B invoices using the Invoice Furnishing Facility (IFF) by the 13th).

3. Benefits of Timely GSTR-1 Filing

  • Protects Buyer Relationships: When you file on time, your invoices auto-populate in your buyer’s GSTR-2B. This ensures they can claim full ITC without having their funds blocked.

  • Smooth GSTR-3B Reconciliation: Your outward tax liability auto-populates directly into your GSTR-3B, preventing calculation mismatches or scrutiny from the GST portal.

  • Maintains High Compliance Rating: Consistent, on-time filings avoid red flags and automated notices from the tax authorities.

4. What Happens If You Miss the Deadline?

Missing tomorrow’s deadline triggers strict automated restrictions:

Consequence Statutory Rule / Impact
Daily Late Fees ₹50/day (₹25 CGST + ₹25 SGST) for regular returns; ₹20/day (₹10 CGST + ₹10 SGST) for Nil returns, under Section 47.
Buyer’s ITC Blocked Your invoices will not reflect in the buyer’s GSTR-2B for this tax period, which often leads to withheld vendor payments.
E-Way Bill Generation Blocked Failing to file GSTR-1 for two consecutive tax periods leads to the automated blocking of your E-Way Bill facility under Rule 138E.
Subsequent Filing Lockout Under Rule 59(6), you are barred from filing the subsequent period’s GSTR-1 until the previous GSTR-3B is filed.

File Seamlessly with MLG Associates

Reconciling sales registers, checking HSN summaries, and uploading large invoice batches under tight deadlines can be challenging.

MLG Associates provides:

  • E-invoice verification and HSN-wise error resolution.

  • B2B vs. GSTR-2B alignment to protect buyer relationships.

  • Timely, compliant e-filing across monthly and quarterly GST cycles.

Don’t let late fees and blocked buyer credits hurt your business reputation. Contact MLG Associates today to finalize and file your GSTR-1 before the deadline closes.
Useful Links:-
Official GST Common Portal:- https://www.gst.gov.in/
CBIC Central Tax Notification:- https://www.cbic.gov.in/
E-way Bill System :- https://ewaybillgst.gov.in/
MLG Associates:- https://mlgassociates.in/
Advance Tax Due Date Reminder: Pay 2nd Installment by 15th September | MLG Associates

Advance Tax Due Date Reminder: Secure Your 2nd Installment by September 15

The second quarter of the financial year is closing, which means the September 15 deadline for your second Advance Tax installment is rapidly approaching. Failing to estimate your income correctly or missing this deadline can lead to compounding penal interest.

Here is a comprehensive guide to understanding, calculating, and paying your second advance tax installment.

Who is Legally Required to Pay Advance Tax?

The “Pay As You Earn” scheme applies to almost everyone generating substantial income outside of a standard salary where TDS is fully deducted. You must pay advance tax if your total estimated tax liability for the financial year (after deducting TDS/TCS) is ₹10,000 or more.

  • Salaried Individuals: If you earn significant additional income (e.g., rental income, capital gains from stocks/mutual funds, high-interest income, or dividends).

  • Business Owners & Corporates: All companies, partnership firms, and LLPs.

  • Freelancers & Professionals: Consultants, doctors, lawyers, and gig workers.

  • Exemption: Resident senior citizens (aged 60 or above) who do not have any income from a business or profession are entirely exempt from paying advance tax.

  • Presumptive Taxation (Section 44AD/44ADA): Taxpayers under this scheme do not pay quarterly; their single deadline for 100% advance tax is March 15.

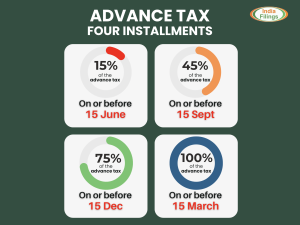
Advance Tax Installment Schedule (Standard Taxpayers)

Due Date Cumulative Tax Payable Amount to be Paid in this Quarter
On or before June 15 15% of total tax liability 15%
On or before September 15 45% of total tax liability 30% (45% minus what was paid in Q1)
On or before December 15 75% of total tax liability 30%
On or before March 15 100% of total tax liability 25%

How to Calculate Your September 15 Liability (With Example)

You don’t need to know your exact year-end income, but you must make an accurate projection.

  1. Estimate Gross Income: Add up your expected salary, business profits, rent, interest, and capital gains for the entire financial year.

  2. Apply Deductions: Subtract your planned Chapter VI-A deductions (80C, 80D, etc.).

  3. Calculate Total Tax: Apply the current income tax slab rates (Old or New Regime) to your net estimated income.

  4. Deduct TDS/TCS: Subtract any tax that has already been deducted at the source by your employer, clients, or banks.

  5. Calculate the 45% Target: Multiply the remaining tax liability by 45%. Subtract any amount you already paid in the June 15 installment.

Practical Example: Mr. Sharma estimates his total net tax liability for the year (after TDS) to be ₹1,00,000.

  • By June 15: He paid 15% (₹15,000).

  • By Sept 15: He needs to reach 45% cumulative (₹45,000).

  • Payment Due Now: ₹45,000 (Target) – ₹15,000 (Already Paid) = ₹30,000.

Penalties for Missing the September 15 Deadline

The Income Tax Department is strict about timely collections. Shortfalls trigger mandatory interest:

  • Section 234C (Shortfall in Installments): If your September payment falls short of the 45% target, you will be charged 1% interest per month for 3 months on the shortfall amount. (Note: A slight leniency is given if you pay at least 36% by Sept 15, avoiding 234C for this specific quarter).

  • Section 234B (Default in Payment): If your total advance tax paid by the end of the financial year is less than 90% of the assessed tax, you will face an additional 1% interest per month starting from April 1 of the following year until the tax is fully paid.

Step-by-Step Online Payment Guide

  1. Visit the official e-Filing portal (incometax.gov.in).

  2. Navigate to e-Pay Tax (you can do this pre-login or post-login).

  3. Enter your PAN/TAN and verify via OTP.

  4. Select the Income Tax box and choose the correct Assessment Year (e.g., AY 2027-28 for FY 2026-27).

  5. Select Payment Type as Advance Tax (100).

  6. Enter the tax amount and pay via Net Banking, Debit Card, NEFT/RTGS, or UPI.

  7. Crucial: Download and save the Challan Receipt (CRN/BSR code) to report in your final ITR.

MLG Associates

Expert Tax Planning with MLG Associates

Estimating income halfway through the year—especially when dealing with fluctuating business revenue or complex capital gains—can be tricky. Overpaying locks up your working capital, while underpaying triggers harsh penalties.

How MLG Associates can help:

  • Accurate financial year income projections and tax slab optimization.

  • Timely calculations of specific installments adjusting for dynamic capital gains.

  • Complete management of your e-payments and challan documentation.

  • Strategic advisory to maximize your deductions before the year ends.

Don’t let penal interest eat into your profits. Contact MLG Associates today to accurately calculate and file your Advance Tax before the September 15 deadline.
Website :- https://mlgassociates.in/
Youtube:- https://www.youtube.com/@SangeetGuptaFinsysERPSoftware

Capital Gains Tax on Real Estate: 12.5% Rate vs Indexation Benefit Explained | MLG Associates

Capital Gains Tax on Real Estate: Navigating the 12.5% Rate, Grandfathering Relief, and Indexation Rules

The taxation framework governing capital gains on immovable property underwent substantial restructuring following statutory amendments to the Income-tax Act, 1961. For property owners, investors, and corporate entities, understanding how long-term capital gains (LTCG) are calculated is critical for optimizing tax liability and staying compliant.

This guide breaks down the updated tax slabs, holding periods, the dual-computation safeguard for pre-existing properties, and key strategic considerations for taxpayers.

1. Key Highlights of the Capital Gains Overhaul

  • Revised Long-Term Capital Gains Rate: The baseline tax rate for LTCG on immovable property (land, buildings, or both) stands at 12.5% without indexation (down from the earlier 20% with indexation).

  • Standardized Holding Period: The qualifying period for classifying immovable property as a long-term capital asset remains 24 months.

  • Withdrawal of Cost Inflation Index (CII): For properties acquired on or after July 23, 2024, indexation benefits under the second proviso to Section 48 are completely removed.

2. The Grandfathering Safeguard: Second Proviso to Section 112(1)(a)

To protect existing property owners from retrospective tax burdens on historical inflation, Parliament enacted a grandfathering mechanism via the Second Proviso to Section 112(1)(a).

Eligibility Criteria:

This relief applies exclusively when all of the following conditions are met:

  1. The taxpayer is a Resident Individual or a Resident Hindu Undivided Family (HUF).

  2. The asset is land, building, or both.

  3. The asset was acquired before July 23, 2024.

  4. The transfer/sale takes place on or after July 23, 2024.

Important Exclusion: This grandfathering relief is not available to Non-Resident Indians (NRIs), Companies, LLPs, or Partnership Firms. For these entities, the tax is levied strictly at 12.5% without indexation.

3. How the Dual Computation Mechanism Works

For eligible resident individuals and HUFs selling properties acquired prior to July 23, 2024, indexation acts as a statutory tax ceiling. Taxpayers are required to compute tax liability under two parallel methods:

Method Tax Calculation Basis Applicable Rate
New Regime Sale Consideration − Actual Cost of Acquisition 12.5%
Old Regime (Ceiling Check) Sale Consideration − Indexed Cost of Acquisition (CII) 20%

Final Tax Payable: The taxpayer pays the lower of the two computed tax figures.

  • High-Growth Assets: If the property has appreciated significantly above inflation, the 12.5% without indexation route yields lower tax.

  • Modest-Growth Assets: If property appreciation was low or moderate over a long period, computing at 20% with indexation caps the tax at a lower amount or even zero.

4. Capital Gains Tax Comparison: Illustrative Case Study

Consider a resident individual selling a residential plot in AY 2026-27 (acquired in FY 2011-12):

  • Purchase Price (2011-12): ₹50,00,000

  • Indexed Cost of Acquisition: ₹98,00,000 (illustrative based on CII)

  • Sale Consideration: ₹1,20,00,000

Metric Option A: New Law (12.5% without Indexation) Option B: Old Law (20% with Indexation)
Gross Consideration ₹1,20,00,000 ₹1,20,00,000
Deductible Cost ₹50,00,000 (Purchase Price) ₹98,00,000 (Indexed Cost)
Net Capital Gain ₹70,00,000 ₹22,00,000
Tax Rate 12.5% 20.0%
Computed Tax ₹8,75,000 ₹4,40,000
Final Tax Payable ₹4,40,000 (Tax capped under 2nd Proviso to Sec 112(1)(a))

5. Rollover Exemptions (Sections 54, 54EC, and 54F)

Taxpayers reinvesting real estate proceeds must note:

  • Section 54 & 54F: Exemptions for purchasing or constructing residential property continue to be available. Reinvestment calculations must be synchronized with the dual computation mechanism.

  • Section 54EC: Capital gains bonds (REC, PFC, NHAI) remain capped at a maximum investment of ₹50 Lakhs per financial year.

Optimize Your Real Estate Tax Strategy with MLG Associates

Determining the exact tax liability under the dual-computation regime requires careful analysis of historical cost inflation indices, registration values, improvement expenses, and exemption structuring.

MLG Associates provides:

  • Comparative dual-computation reporting for legacy property transactions.

  • Advisory on Section 54, 54EC, and 54F capital gains reinvestment schemes.

  • Capital gains tax computation and compliance for resident individuals, NRIs, and corporate entities.

Contact our direct tax advisory team at MLG Associates for structured tax planning before executing any high-value real estate transaction.

References & Legal Sources

  1. The Finance (No. 2) Act, 2024 — Amendments to Section 48 and Section 112 of the Income-tax Act, 1961.

  2. Income Tax Department, Government of India — Official provisions on Section 112 (Tax on Long-Term Capital Gains).

  3. Central Board of Direct Taxes (CBDT) — Notifications regarding Cost Inflation Index (CII) and real estate capital gains grandfathering guidelines.

Car Perquisite Rules 2025 vs 1961: Strategic Tax Guide

Car Perquisite Rules Under Income Tax Act, 2025 vs. 1961 Act: A Practical Guide for CFOs & Employers

The tax rules surrounding employee salary structures in India have undergone a major update. With the implementation of the Income Tax Act, 2025, the government has revised several age-old financial limits to match current inflation and modern corporate realities.

One of the most practical changes impacts Motor Car Perquisites—a common perk offered to executives and managers across corporate India.

For CFOs, HR leaders, and business owners, understanding these updated rules is crucial to manage monthly TDS deductions correctly, avoid compliance errors, and help employees optimize their take-home salary.

In this article, MLG Associates breaks down the revised motor car tax rules in plain professional language and compares the Income Tax Act, 1961 with the Income Tax Act, 2025.

Why Were the Old Rules Changed?

Under the previous Income Tax Act, 1961, the standard perquisite values for company cars (ranging from ₹600 to ₹2,400 per month) were fixed decades ago.

Over time, vehicle prices, fuel costs, and driver salaries went up significantly, but these tax limits remained unchanged. The Income Tax Act, 2025 resets these standard limits to reflect real-world running costs while keeping the tax calculation process simple and straightforward.

Simple Breakdown: Old Rules (1961 Act) vs. New Rules (2025 Act)

How a car is taxed depends on three basic questions:

  1. Who owns or hires the car? (Employer or Employee)
  2. How is it used? (Official use, Personal use, or Mixed use)
  3. What is the engine size? (Up to 1.6 Liters / 1,600 cc vs. Above 1.6 Liters)

Important Rule:

  • If a company car is used 100% for official work, there is zero tax, provided proper logbooks and company certificates are maintained.
  • If used 100% for personal work, the actual total cost incurred by the employer (fuel + driver + maintenance + 10% yearly car depreciation) is added directly to the employee’s taxable salary.

For vehicles used for both official and personal purposes (mixed usage), the updated monthly taxable perquisite values are as follows:

Comparative Table: Taxable Perquisite Value Per Month

Category & Vehicle Ownership Usage & Expense Condition Engine Capacity / Details Old Law (1961 Act) New Law (2025 Act)
Category A: Employer Owned/Hired Car Expenses met or reimbursed by Employer (Used for Official & Personal) • Engine Capacity ≤ 1.6 Liters


• Driver / Chauffeur Addition

₹1,800 / month


+ ₹900 / month

₹5,000 / month


+ ₹3,000 / month

• Engine Capacity > 1.6 Liters


• Driver / Chauffeur Addition

₹2,400 / month


+ ₹900 / month

₹7,000 / month


+ ₹3,000 / month

Category B: Employer Owned/Hired Car Personal running expenses borne by Employee (Used for Official & Personal) • Engine Capacity ≤ 1.6 Liters


• Driver / Chauffeur Addition

₹600 / month


+ ₹900 / month

₹2,000 / month


+ ₹3,000 / month

• Engine Capacity > 1.6 Liters


• Driver / Chauffeur Addition

₹900 / month


+ ₹900 / month

₹3,000 / month


+ ₹3,000 / month

Category C: Employee Owned Car Expenses reimbursed by Employer (Used for Official & Personal) • Engine Capacity ≤ 1.6 Liters Actual expense minus ₹1,800/mo Actual expense minus ₹5,000/mo
• Engine Capacity > 1.6 Liters Actual expense minus ₹2,400/mo Actual expense minus ₹7,000/mo
• Driver / Chauffeur Addition Minus ₹900/mo extra Minus ₹3,000/mo extra
Category D: Employee Owned Two-Wheeler Expenses reimbursed by Employer (Used for Official & Personal) • Any Engine Capacity Actual expense minus ₹900/mo Actual expense minus ₹3,000/mo

Key Takeaways for Businesses and Payroll Teams

  1. Higher Taxable Income for Senior Executives (Company Cars):

For senior executives using company-provided luxury cars (>1.6L with a driver), the taxable perquisite jumps from ₹3,300/month (₹39,600/year) to ₹10,000/month (₹1,20,000/year). This increases monthly TDS withholdings, which may slightly reduce their net monthly pay if compensation structures stay the same.

  1. Bigger Tax Benefit for Employee-Owned Cars:

If employees use their own cars for work and claim reimbursements, the tax deduction limit has been increased from ₹1,800 / ₹2,400 up to ₹5,000 / ₹7,000 per month (plus ₹3,000 per month for driver reimbursement). This significantly reduces taxable income for field staff and managers.

  1. 3x Higher Relief for Two-Wheelers:

Reimbursement limits for employee-owned two-wheelers used for official duty have tripled from ₹900 per month to ₹3,000 per month, benefiting sales, logistics, and field service employees.

Strategic Roadmap: How Businesses & Employees Can Maximize Benefits Under the 2025 Act

To make the most of these revised limits and reduce tax impact legally, organizations and employees should adopt the following actionable strategies:

  • Shift to “Employee-Owned, Employer-Reimbursed” Models:

Since deduction limits for employee-owned vehicles have increased significantly (up to ₹7,000 + ₹3,000 per month), restructuring allowances into fuel and vehicle allowance reimbursement programs can yield higher tax-free take-home pay compared to offering company-owned vehicles.

  • Re-evaluate Executive Car Policy:

For senior leaders using company cars, review if switching from a company-provided car model to a structured car lease / reimbursement model delivers better overall net tax benefits under the 2025 Act.

  • Maintain Digital Logbooks for 100% Official Claims:

If field staff or executives use vehicles predominantly for official duty, maintain clear digital travel logs (date, distance, purpose, destination, fuel bills). Proving business usage eliminates the perquisite tax completely during tax audits.

  • Update Payroll & ERP Software Immediately:

Finance teams must adjust the tax calculation formulas in their payroll systems (SAP, Finsys, Tally, etc.) to apply the correct 2025 limits and avoid miscalculating TDS under Section 192.

How MLG Associates Can Assist Your Organization

At MLG Associates, our tax and payroll advisory team helps companies adjust smoothly to evolving tax frameworks.

Our services include:

ITR Filing AY 2026-27: Why You Must Reconcile Records First ?

Income Tax Advisory: Why Taxpayers Must Reconcile Key Financial Records Before Filing ITR for AY 2026-27

The Income Tax Department has officially issued an advisory urging all taxpayers to meticulously verify and reconcile their financial information before submitting their Income Tax Returns (ITR) for the Assessment Year (AY) 2026-27 (corresponding to the Financial Year 2025-26).

With advanced data analytics and automated mismatch flags on the e-filing portal, proactive cross-checking has become the single most critical step to ensure error-free filing, prevent statutory notices, and facilitate faster refund processing.

The Core Mandate: Form 16 vs. AIS vs. Form 26AS

The tax department has emphasized that a seamless tax filing experience relies heavily on matching information across three primary pillars of financial reporting:

  1. Form 16 / 16A: The standard TDS certificates provided by employers and deductors.

  2. Annual Information Statement (AIS): The central repository capturing near real-time details of all transactions including dividend payments, stock trading, high-value purchases, savings interest, and mutual fund transactions.

  3. Form 26AS: The official tax credit statement showing the tax actually deposited with the government against your PAN.

Expert Insight from MLG Associates: Even a minor variance between the income declared in your ITR and the auto-populated figures in your AIS can trigger an automated compliance notice under the newly active risk management frameworks.

Step-by-Step Pre-Filing Reconciliation Checklist

To ensure your filing remains highly compliant and free from structural discrepancies, follow this sequence of data validation before hitting the submit button:

1.Download Latest Statements: 

Log in to your e-filing portal profile to pull the most recent, updated copies of your AIS, TIS (Taxpayer Information Summary), and Form 26AS. Do not rely on old drafts as third-party data updates continuously.

2.Cross-Verify Income Streams:

Match your actual salary slips, bank passbook interest credits, and brokerage capital gains statements line-by-line against the corresponding segments in the AIS.

3.Reconcile TDS Credits:

Verify that every rupee of tax deducted by your employer, bank, or clients as shown in your Form 16/16A is accurately credited and fully visible in Form 26AS.

4.Rectify Data Errors in AIS:

If you spot duplicate or erroneous entries reported by a bank or broker in your AIS, use the online feedback mechanism on the tax portal to dispute it prior to filing your return.

Consequences of Neglecting Financial Reconciliation

Filing your ITR in a hurry without side-by-side reconciliation can have immediate negative consequences for both individual and corporate taxpayers:

  • Selection for Compulsory Scrutiny: Unresolved mismatches between reported income and portal data automatically flag the return under the Computer-Assisted Scrutiny Selection (CASS) parameters.

  • Delayed Tax Refunds: The tax department stalls refund processing until any visible discrepancies between the computed tax and the 26AS tax ledger are completely accounted for.

  • Defective Return Notices: If the structural classification of income (e.g., Business Income vs. Capital Gains) contradicts third-party banking records, the return may be deemed legally defective.

Summary Checklist for Taxpayers

Document Type Crucial Checkpoints Mismatch Impact
Form 16 / 16A Verify correct PAN, deduction sections, and total gross salary. Mismatches invalidate TDS deduction claims.
Annual Information Statement Check mutual fund redemptions, foreign remittances, and dividends. Unreported items invite unexpected tax demands.
Bank Statements Capture savings interest and fixed deposit earnings accurately. Omission triggers standard underreporting penalties.

Stay Ahead of the Deadlines

The e-filing windows for AY 2026-27 are actively operational. Taxpayers are strongly advised to initiate their compilation and auditing workflows well before the standard deadlines—July 31, 2026, for non-audit individual profiles and August 31, 2026, for non-audit business structures.

For complex corporate portfolios, high-net-worth individual portfolios, and complex capital gains reconciliations, structural errors can lead to expensive litigations.

Need professional help in streamlining your financial reporting or running a comprehensive pre-filing tax simulation? Reach out to our specialized tax advisory desk at MLG Associates for expert guidance.

LInks:-

https://mlgassociates.in/
https://finsys.co.in/

WordPress Image Lightbox